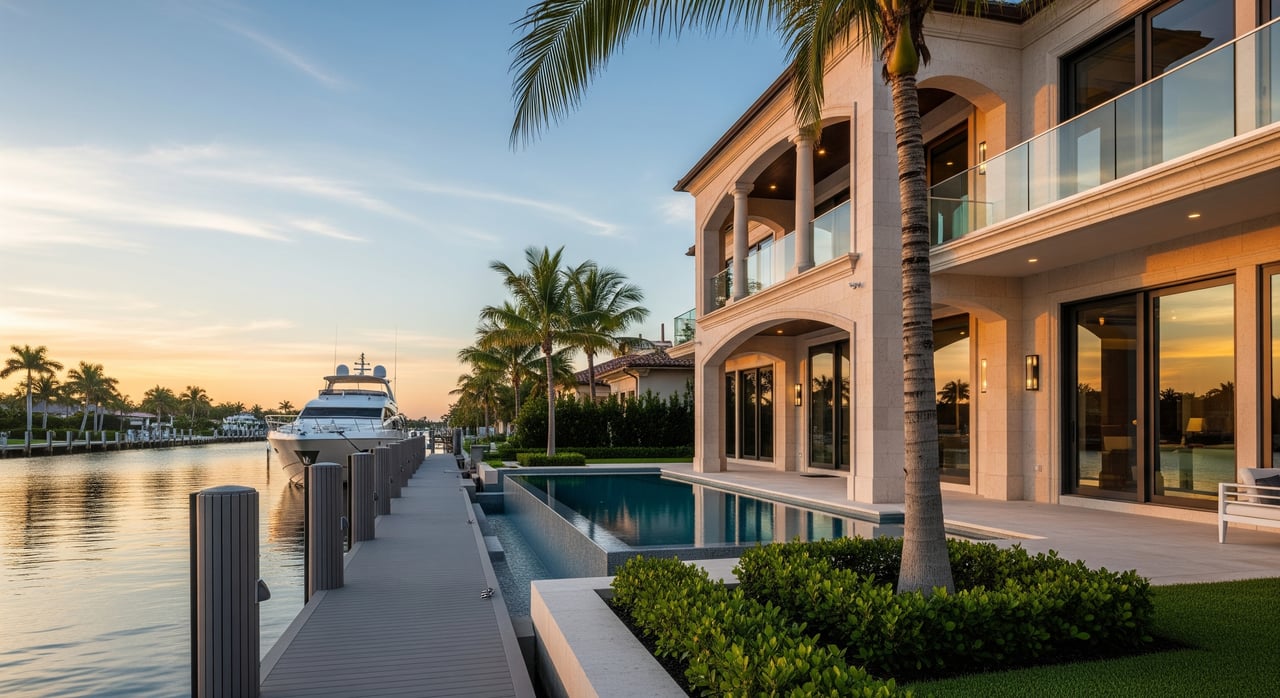
Shopping Bel Marra waterfront homes but not planning to pay all cash? You are not alone. Many Boca Raton buyers use jumbo financing to preserve liquidity, manage risk, or align with a broader wealth plan. In this guide, you will learn how jumbo loans work, what lenders typically require, the alternatives high-net-worth buyers use, and the waterfront-specific items to check before you make an offer. Let’s dive in.
What is a jumbo loan
A jumbo loan is any mortgage that exceeds the federal conforming loan limit set each year by the Federal Housing Finance Agency. Because these loans are non-conforming, lenders use their own guidelines or sell to private investors.
In practical terms, most Bel Marra price points sit above conforming limits, so jumbos are common when buyers do not pay cash. Expect stricter underwriting, more documentation, and appraisal standards tailored to unique waterfront properties.
Why jumbo is common in Bel Marra
Bel Marra is a luxury waterfront enclave where purchase prices often exceed conforming thresholds. Buyers here tend to have strong liquidity, high credit profiles, and significant verified assets. Second-home and investment purchases are frequent, which can influence down payment, reserves, and rate pricing.
Because properties are unique and comps can be limited, lenders place extra focus on valuation, insurance, and title details like seawalls and docking rights.
Typical lender requirements
Every lender sets its own rules, but you can expect the following themes:
- Credit score: Many lenders target mid-700s or higher for top pricing. Lower scores may still qualify with larger down payments and higher rates.
- Down payment and LTV: Primary residences often start around 20 percent down. Second homes and investments can require 25 to 30 percent or more.
- Debt-to-income: Caps are tighter than conforming. Strong assets and reserves help.
- Cash reserves: Luxury lenders often require 12 to 24 months of total housing payments in reserves. Second homes and investments may need more.
- Income documentation: Salaried buyers provide recent pay stubs, W-2s, and two years of returns. Self-employed buyers provide two years of personal and business returns and may need profit and loss statements.
- Assets and source of funds: Expect full bank, brokerage, and retirement account statements. Large transfers require paper trails for compliance.
- Appraisal and valuation: Waterfront homes may need a specialty appraisal or additional review due to limited comparable sales.
- Insurance and title: Lenders verify homeowner’s, flood, and windstorm coverage and review title for seawalls, easements, and HOA restrictions.
Document checklist to prepare
Getting organized early speeds up underwriting and helps you close on time. Start gathering:
- Government ID and recent credit authorizations
- Two months of bank and brokerage statements for all accounts used for funds or reserves
- Retirement account statements if counted as reserves
- Recent pay stubs and W-2s, plus two years of tax returns
- For self-employed: two years personal and business returns, year-to-date profit and loss, and business bank statements
- Evidence of any bonuses, RSUs, K-1s, or passive income
- Source-of-funds letters for gifts or large deposits
- Homeowner’s, flood, and windstorm insurance quotes
- HOA documents, budgets, and any special assessment notices
- Title items relating to seawalls, docking rights, and easements
- Any prior surveys, elevation certificates, and recent inspections
Plan for extra lead time to collect asset statements, tax transcripts, and any specialty appraisal or engineering reports.
Asset-based and alternative options
Well-qualified buyers sometimes choose structures that better match their income or balance sheet. Common choices include:
Conventional jumbo, full-doc
This is the standard path with W-2s or tax returns and full asset verification. It usually delivers the most competitive pricing for buyers who can document steady income.
Bank-statement programs
Self-employed buyers can qualify using business or personal bank statements in place of tax returns. Requirements vary by lender. These programs can help when cash flow is strong but reported taxable income is lower.
Asset-depletion loans
With asset-depletion, lenders convert eligible liquid assets into a calculated monthly income stream. This suits high-net-worth clients who rely on investments rather than wages. Each lender uses its own formulas, so terms and eligible asset types differ.
Portfolio loans with private banks
Portfolio lenders hold loans on their balance sheet and can be more flexible on income, property type, or structure. Relationship pricing may apply when you bring deposits or investments. Terms can be bespoke, though rates are not always the lowest.
Securities-backed lending
Some buyers borrow against a brokerage account to fund a purchase. This can be fast and may avoid placing a mortgage on the home, but it brings market risk. Margin calls can force asset sales if markets drop, so compare total cost and risk before choosing this approach.
Jumbo HELOCs and piggybacks
A line of credit or second mortgage can supplement a first-lien loan. This can help manage cash flow, avoid crossing a pricing tier, or keep financing flexible. Availability and pricing change with market conditions.
Interest-only and ARMs
Interest-only periods and adjustable-rate structures can make sense if you expect a shorter hold or variable cash flow. These products reduce initial payments but add rate and payment-reset risk.
Rates, costs, and timing
Several factors shape your final rate and monthly payment:
- Market conditions: Treasury yields and Federal Reserve policy influence overall mortgage pricing. Jumbo spreads move with investor appetite.
- Borrower profile: Credit score, LTV, loan size, occupancy, and documentation type all affect pricing.
- Relationship pricing: Private banks may offer favorable terms for clients with meaningful deposits or investments.
- Points and buydowns: You can pay points to lower the rate. Calculate your breakeven based on how long you plan to hold the home.
- Rate locks: Many jumbo locks run 30 to 60 days, with longer options for complex deals. Discuss lock fees and float-down features.
Closing costs for luxury waterfront homes are higher in absolute dollars. Title premiums scale with price, and third-party inspections, surveys, and association fees add up. While not a closing cost, budget for flood and windstorm insurance because they are material to monthly carrying costs.
Expect the timeline to look similar to a conforming loan, with possible extensions for specialty appraisals, HOA processing, and insurance underwriting. Build in time for appraisal review and any renegotiation if the value comes in below contract.
Waterfront due diligence in Bel Marra
Waterfront properties come with extra layers of review that matter to your lender and to your risk profile:
- Flood zone and insurance: Confirm FEMA flood zone, elevation, and whether you need National Flood Insurance Program or private coverage. Premiums depend on structure and elevation and can influence affordability.
- Windstorm and hurricane exposure: Lenders expect adequate wind coverage. Wind-mitigation features like shutters and roof strapping can reduce premiums when documented.
- Seawalls and docking: Verify ownership and maintenance responsibilities, permitted status, and condition. Title should clarify riparian rights and any easements.
- Appraisal complexity: Unique homes, custom finishes, and dock features can limit comps. A specialty appraiser or second opinion may be required.
- HOA and permitting: Review association financials, rules, any special assessments, and docking permits. Understand renovation restrictions.
- Additional inspections: Consider piling or foundation checks, termite, mold, and storm-related structural reviews as needed.
Clarify intended occupancy early. Primary, second home, and investment classifications carry different LTV, reserve, and pricing standards.
Cash vs financing: how to decide
Even if you can pay cash, financing can preserve liquidity, maintain portfolio positioning, and add flexibility for renovations or future purchases. The tradeoffs are interest cost, documentation, and the time needed to close. If you choose an alternative path like securities-backed lending, weigh market risk and potential tax outcomes.
A simple framework helps:
- If you value liquidity and expect to hold the home longer, compare a full-doc jumbo at various points to your expected portfolio returns.
- If you are self-employed with strong cash flow but complex tax returns, explore bank-statement or asset-depletion options.
- If speed is critical, ask about portfolio lending timelines and whether your existing banking relationships can shorten the process.
How to get started
- Verify the current FHFA conforming limit for this year and confirm whether your target price requires a jumbo.
- Speak with a lender experienced in Florida waterfront jumbos to map documentation, reserves, and timing.
- Request early quotes for homeowner’s, flood, and windstorm coverage based on the property’s elevation and features.
- Order a jumbo-specific pre-approval that reflects your true occupancy type and loan structure.
- Line up HOA documents, recent surveys, and any elevation certificates before you go to contract.
- Engage a coastal-savvy appraiser and a real estate attorney who understands seawalls and docking rights.
When you want a polished plan and a seamless experience, partner with a local team that deals in these details every day. For curated listings, lender introductions, and a step-by-step path to closing in Bel Marra, connect with Dana Ocampo and the Dana and Mandy Team.
FAQs
What is a jumbo loan for Bel Marra waterfront homes
- A jumbo is any mortgage above the FHFA conforming limit for the year, so lenders use non-conforming guidelines and stricter documentation.
How much down do I need for a Boca jumbo
- Many buyers bring 20 percent down for primary homes, while second homes and investments often require 25 to 30 percent or more depending on the lender.
How long does a jumbo loan take in Palm Beach County
- Timelines can mirror conforming loans, but add time for specialty appraisals, HOA processing, insurance review, and asset verification.
Will my appraisal match the contract price on a unique waterfront home
- It might not, because comps are limited; options include renegotiating, increasing your down payment, or providing additional comparable sales for review.
How much will flood and wind insurance cost in Bel Marra
- Costs vary by FEMA zone, elevation, year built, mitigation features, and coverage levels, so request quotes early to confirm affordability.
Can I use investments instead of income to qualify
- Yes, asset-depletion and securities-backed options exist, but terms and risks vary, so compare total cost, flexibility, and market risk before choosing.
Are interest-only or ARM jumbo loans smart for seasonal owners
- They can lower initial payments and suit shorter holds, but they carry rate and payment-reset risk, so model scenarios before committing.